
Jo Thompson Recruitment contributes to the Report on Jobs, a comprehensive guide to the UK labour market produced by KPMG and the Recruitment & Employment Confederation (REC), and compiled by S&P Global. This monthly report draws on survey data from recruitment consultancies to provide insights into the latest labour market trends.
September’s data shows a further modest improvement in recruitment activity nationally, with permanent placements rising for a second month and temporary billings continuing to increase. Vacancies are still falling, but at their slowest rate in just over two years. The South of England remains behind the national recovery, with permanent hiring declining again and temporary growth losing momentum.
Commenting on the latest survey results, Jon Holt, Group Chief Executive and UK Senior Partner at KPMG, said:
“For the second month in a row we are seeing the jobs market starting to flicker back to life, with businesses increasing their hiring across both permanent and temporary roles, and for the first time in over two years vacancies grew in the private sector.
“But this remains a fragile recovery; and in some sectors it could be seen as an employer’s market as the number of people looking for roles increases. The growing uncertainty around energy prices and higher borrowing costs also means there are still headwinds in the wider economy. Businesses will be looking to the Budget later this month for greater certainty in tax policy and a sense that the Government is willing to create the right conditions to turn this emerging confidence into investment and ultimately jobs.”
Maxine Bligh, Interim Chief Executive at the Recruitment and Employment Confederation (REC), said:
“The permanent jobs market is revving its engine, with a second successive month of growth. The last time we saw a sustained run of growth in permanent placements was between March 2021 and September 2022. If this trend continues, we could see genuine momentum building across the labour market, with both permanent and temporary hiring moving in the same direction, which is encouraging for jobseekers and the economy. The signal from the private sector is that it is ready to invest, with permanent vacancies rising for the first time in more than two years across the sector. A Budget that gets business confidence moving again is key to keeping that momentum going. The geopolitical backdrop remains challenging for government and business alike. But the Chancellor cannot seize this moment with talk of stability alone. Employers want to hear not just how we deliver stability, but how we go for growth.”
Courtesy of S&P Global, KPMG and the Recruitment & Employment Confederation
Executive Summary
The Report on Jobs provides an early monthly indication of UK labour market trends. The main findings for September are:
Permanent placements rise for a second consecutive month
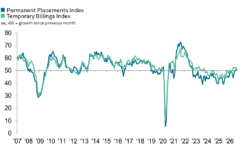
Permanent appointments increased slightly again in September, with the UK Permanent Placements Index rising from 50.5 to 50.9. Although marginal, this was the strongest increase in four years. Recruiters linked the improvement to rising activity, expansion plans and greater business confidence, although recruitment freezes continued to limit growth. Temporary billings also increased, with the index at 50.9, but growth slowed from August and remained modest.
Growth in starting salaries and temporary pay eases
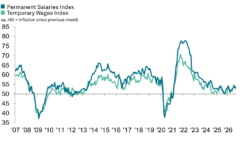
Permanent salary growth slowed for the first time in four months, while temporary wage inflation eased to a four-month low. Competition for highly skilled workers continued to support higher offers, but cost pressures and a larger pool of available candidates helped to moderate increases.
Candidate availability rises at its slowest pace in three years
The overall supply of candidates continued to increase sharply, although growth was the weakest since September 2023. This reflected a slower rise in permanent candidate availability. Temporary candidate numbers increased at their fastest pace in three months, with redundancies and fewer opportunities continuing to contribute to the larger pool of jobseekers.
Vacancies fall more slowly as private sector demand improves
The Total Vacancies Index increased from 47.0 in August to 48.5 in September, indicating the mildest decline in demand since August 2024. Permanent and temporary vacancies both fell modestly overall. However, the separate figures for the private and public sectors, which are not seasonally adjusted, showed the first increase in private sector permanent vacancies for more than two years. Public sector demand continued to fall markedly.
Index readings above 50 indicate an increase compared with the previous month; readings below 50 indicate a decline. The indices measure the direction of change, rather than percentage growth.
Courtesy of S&P Global, KPMG and the Recruitment & Employment Confederation
Staff Availability
Overall candidate supply continues to expand
The Total Staff Availability Index fell from 60.6 in August to 57.2 in September. Candidate supply has now increased for just over three-and-a-half years, but the latest rise was the slowest in three years. Recruiters continued to cite redundancies and fewer job opportunities as reasons for the increase.
Permanent labour supply rises more slowly
The Permanent Staff Availability Index eased from 60.9 to 57.2, signalling the weakest increase since September 2023. Permanent candidate numbers rose across all four monitored English regions. The North recorded the sharpest increase, while London saw only marginal growth. The South’s index stood at 57.8.
Temporary candidate numbers increase at a quicker pace
Temporary candidate availability increased at its fastest pace since June, with the UK index rising from 56.1 to 57.4. Recruiters attributed the increase to fewer vacancies and more people being out of work. The North saw the strongest growth in supply, while London recorded the weakest increase.
Pay Pressures
Permanent salary growth moderates
The Permanent Salaries Index eased from 54.1 in August to 53.4 in September. Starting salaries continued to rise at a solid pace, although growth remained below the historical average. Employers were still prepared to pay more for specialist skills, but greater candidate availability and efforts to manage costs limited increases.
Temporary wage inflation slows to a four month low
The Temporary Wages Index fell from 53.5 to 52.6. Hourly rates continued to rise, but at their slowest pace since May. Wage growth moderated across all four monitored English regions, with the strongest increase in the North and the softest in the Midlands.
KPMG and REC UK Report on Jobs South of England
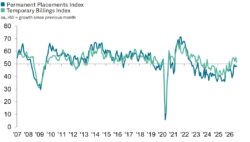
The South of England’s September results were weaker than the national picture. Permanent placements fell for a 42nd consecutive month, with the index easing from 48.6 to 47.9. Temporary billings continued to rise, but the index fell from 55.1 to 51.3, signalling the slowest growth since the current expansion began in April.
Steve Hickman, Reading Office Senior Partner at KPMG UK, said:
“September’s results are a reminder that improvement in the South’s labour market is unlikely to be linear. There were some more encouraging signs over the summer, but permanent hiring fell at a slightly faster pace and growth in temporary billings has slowed, suggesting businesses are reluctant to commit while confidence is fragile and projects are being delayed.
“There are some signs of progress underneath that headline, with the decline in permanent vacancies now at its weakest in two-and-a-half years. But opportunities are still contracting and the South is currently seeing weaker demand than the UK overall, while more people are competing for roles.
“With the Autumn Budget now approaching, businesses will be looking out for measures that give them greater certainty over costs and the confidence to restart investment and recruitment. Until that translates into stronger demand for workers, it will be difficult to call this a sustained improvement.”
Courtesy of S&P Global, KPMG and the Recruitment & Employment Confederation
Staff Availability
Permanent candidate availability rose sharply, although the index fell from 60.3 to 57.8, marking the slowest expansion since January. Redundancies remained a frequent explanation. Temporary candidate supply increased slightly faster than in August, with the index rising from 56.2 to 57.0, as job losses and fewer contract opportunities added to availability.
Pay Pressures
Starting salaries rose modestly, with the Permanent Salaries Index falling from 54.6 to 51.5. This was the slowest increase among the monitored English regions. Temporary pay growth also eased, with the index declining from 53.2 to 52.4. Employers continued to offer more for the right skills and experience, while cost control and subdued economic conditions limited wider increases.
Permanent vacancies fell at their slowest rate in two-and-a-half years, but both permanent and temporary demand remained weaker than the UK average. Each regional vacancies index stood at 46.6 in September.
Special Feature
This month’s special feature draws on REC analysis of the UK recruitment market over summer 2026.
Early signs of recovery over the summer
The REC’s review points to a gradual improvement in recruitment activity, alongside continued caution over costs and the economic outlook. Permanent placements stabilised in July before rising slightly in August, while temporary recruitment continued to provide employers with flexibility.
Job postings remain above last year
The REC Labour Market Tracker recorded 1.70 million active job postings in August, 10.4% more than a year earlier, following 1.67 million in July. New postings were also higher year on year, rising by 0.9% in July and 3.6% in August. All UK Government Office Regions recorded growth in active postings in August, although the strongest local increases were concentrated in Scotland.
These job-posting figures measure a different aspect of recruitment activity from the Report on Jobs survey. Higher postings compared with a year earlier can therefore sit alongside recruiters reporting a monthly decline in vacancies.
Employer confidence improves but remains negative
JobsOutlook found that employer confidence in the economy improved by eight percentage points over June–August to -39%, while confidence in hiring and investment rose six points to -8%. Both remained negative, suggesting that employers were becoming less pessimistic without yet committing to a sustained increase in recruitment.
September’s survey adds to the evidence of a tentative improvement nationally. However, slower temporary growth and continued weakness in the South show that progress remains uneven. A larger pool of available candidates also continues to sit alongside shortages of particular skills.
For employers in the South, reported shortages still include accountants, accounts payable staff, HR business partners and employee relations specialists. Data analysts also feature among the skills in short supply for temporary roles. This suggests that a wider choice of candidates will not remove the need for targeted searches and a clear understanding of the experience each role requires.
Summary
September brought a second month of modest growth in permanent recruitment nationally, together with a slower decline in vacancies. However, the South of England has yet to share fully in that improvement. Permanent hiring continues to fall, temporary growth has softened and employers remain cautious about longer-term commitments.
For employers, the wider pool of available candidates offers opportunities to recruit, while temporary and contract appointments can support projects where flexibility is needed. For candidates, competition remains high, although relevant specialist skills and experience continue to attract demand.
If you’d like to discuss your current recruitment requirements or discover how we can help you attract, assess and retain the very best talent, we’d be delighted to hear from you. Call us on 01635 734975.
Sources: KPMG and REC UK Report on Jobs and South of England Report, September 2026 data, published 8 October 2026. Special feature: REC analysis reproduced in the UK report.